
Quant Trading for Everyone and the Beautiful Chart Trap
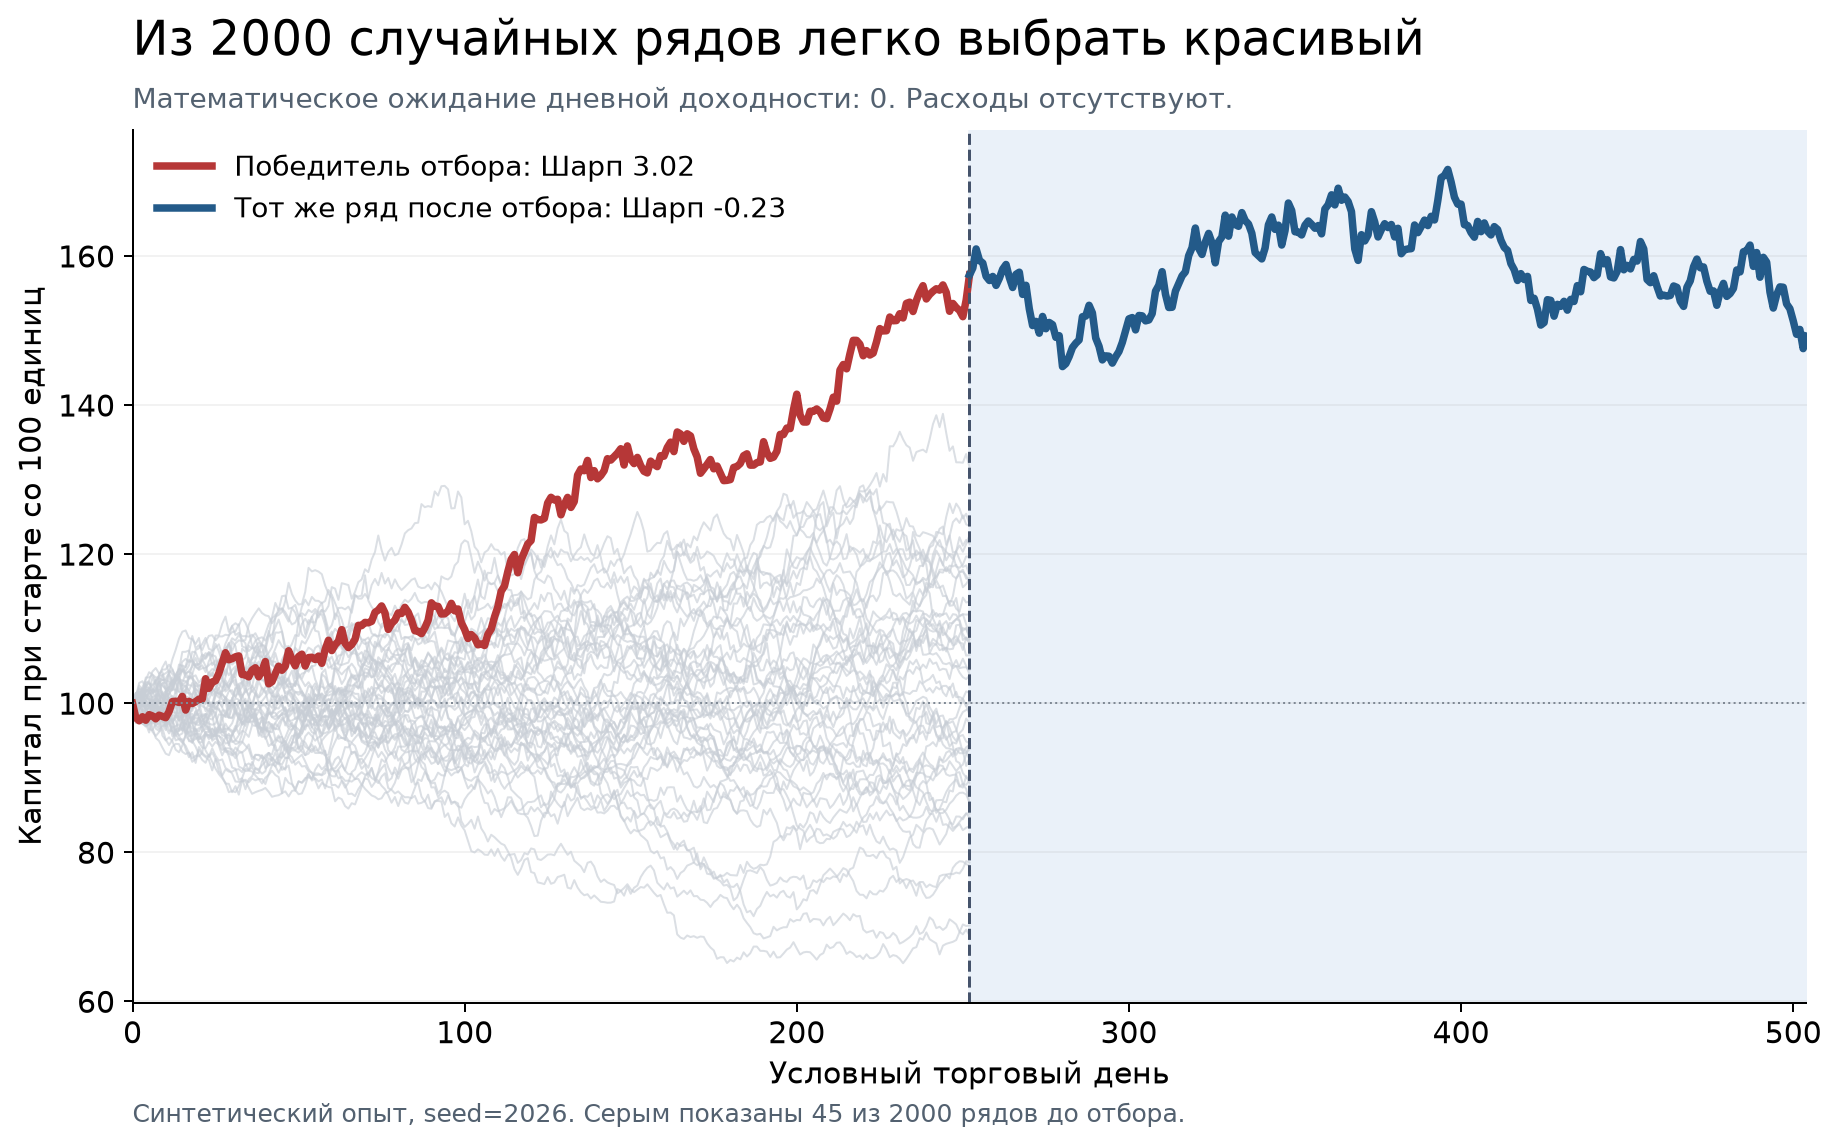
This Habr article explores the risks of building trading bots using modern tools like Freqtrade, LEAN, and vectorbt. The author emphasizes that the ease of developing algorithms often masks a lack of real market edge. The core issue lies in 'overfitting' parameters to historical data, which can generate impressive-looking profit charts from random numbers that inevitably fail in live trading. The article details common pitfalls: data errors, excessive parameter optimization, and ignoring transaction costs. The author urges developers to critically evaluate backtest results, considering the gap between theoretical signals and actual trade execution. This piece serves as a warning for novice algo-traders, reminding them that attractive report figures often hide fundamental design flaws that require rigorous verification and a deep understanding of market mechanics.
This is a summary. Read the full article at the original source:
HabrRelated stories

JPMorgan Chase blocks outside AI agents, limiting what Muse can do for users
JPMorgan Chase has officially blocked third-party AI agents, including Meta’s Muse, from accessing retail customer accounts to perform actions on thei…

Corporate spend management platform Ramp has achieved a significant milestone, reaching a $60 billion valuation. This latest financial achievement coi…
Pulse Local has launched as a new budgeting application designed specifically for macOS, emphasizing user privacy by running all AI models directly on…