
Can you use autoregressive diffusion to generate market data?
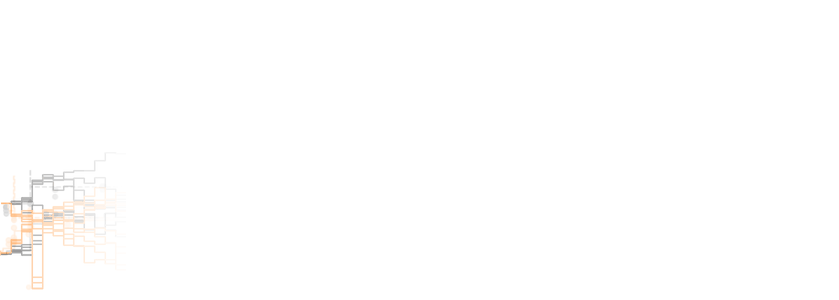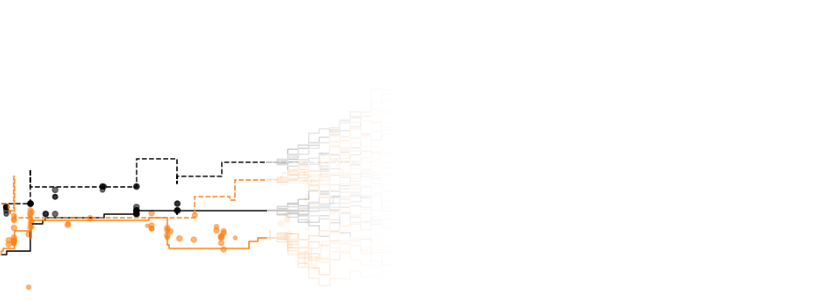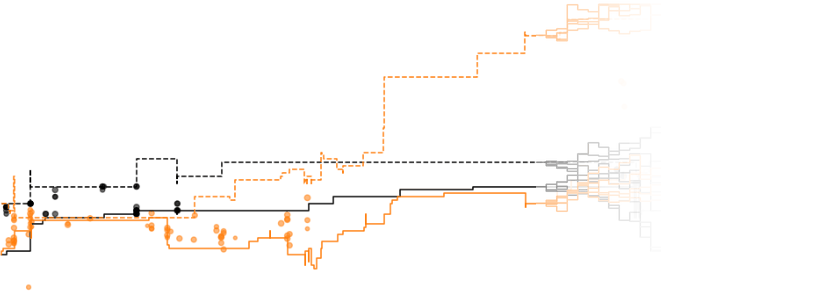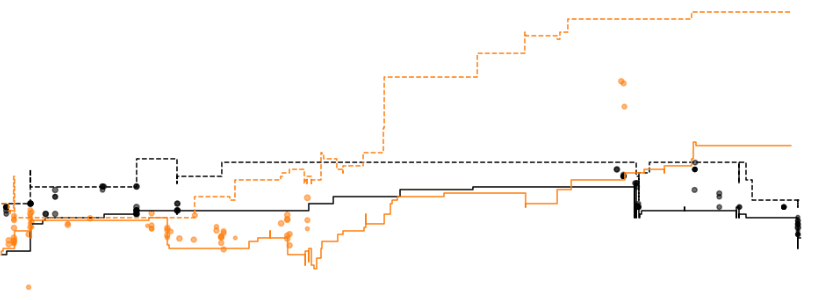
Jane Street researchers explore the application of autoregressive diffusion models to the generation of synthetic financial market data. While diffusion models have gained prominence in image and audio synthesis, their utility in modeling complex, high-frequency time series data remains an active area of investigation. The article examines the technical challenges of applying these probabilistic models to market microstructure, where temporal dependencies and non-stationary distributions are critical. By comparing autoregressive approaches with traditional generative methods, the authors evaluate whether these models can effectively capture the nuances of order book dynamics and price movements. The study highlights the potential for synthetic data to improve backtesting and risk management strategies, while acknowledging the inherent difficulties in replicating the statistical properties of real-world financial markets. This research contributes to the broader discourse on leveraging generative AI for quantitative finance and data augmentation in data-scarce environments.
This is a summary. Read the full article at the original source:
Hacker News (YC)Related stories

In conditions of unstable internet connectivity, accessing modern language models becomes difficult. The author proposes a solution for situations whe…

Nine loops from Claude: Why this is important for the future of scientific code
Anthropic has announced nine-loop calculations for the Claude model, marking a significant advancement in theoretical physics. The author uses this ne…

Anthropic restricts internet access for internal AI agent evaluations
Anthropic has announced a significant change to its safety testing protocols, confirming that it has disabled live internet access for all internal ev…